Market Mastery
Webinar by Vishal Malkan
Find the weak links
in your portfolio by Vishal Malkan
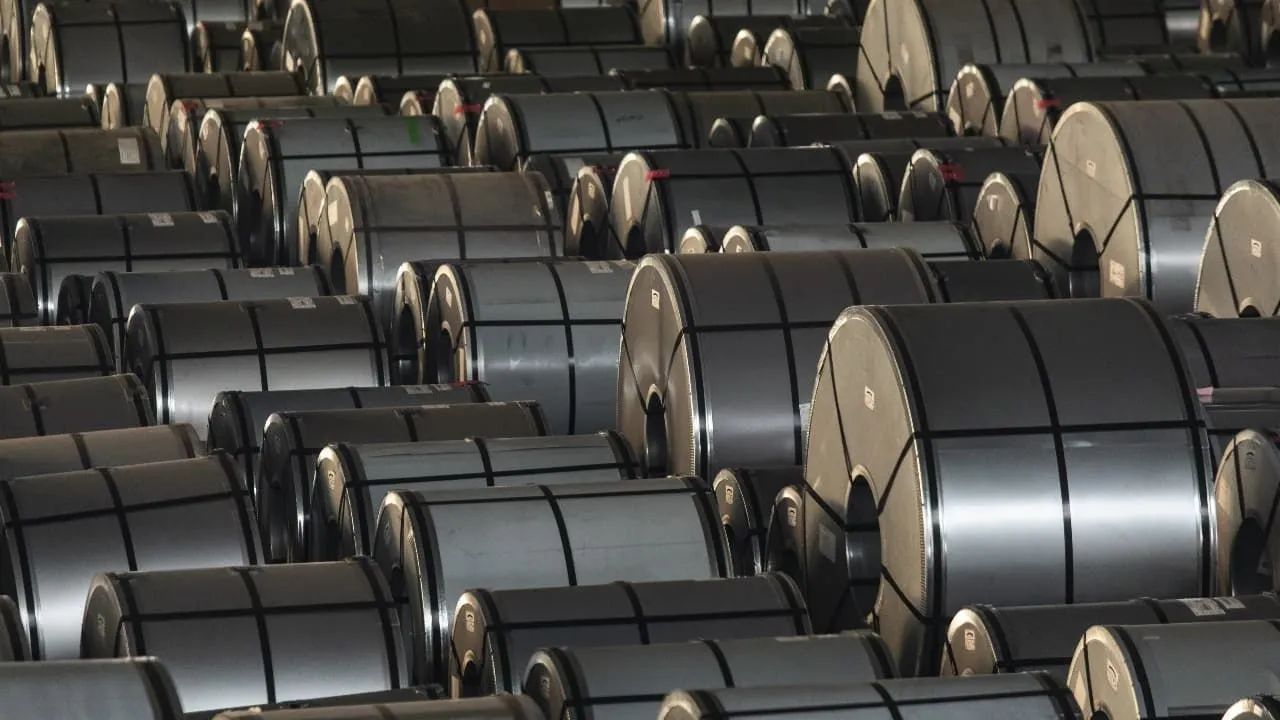
Metal sector stocks witnessed sharp selling on Wednesday, November 18, with the Nifty Metal index declining nearly 2 percent in early trade to emerge as the worst-performing sectoral index on the NSE. Weakness in commodity prices, a stronger US dollar and expectations of higher US interest rates weighed on investors sentiment. Market participants cautious ahead of the release of minutes from the US Federal Reserve's latest policy meeting for clues on the interest rate outlook.
The Nifty Metal index opened at 12,441.85 and fell 1.8 percent to hit an intraday low of 12,301.85, compared with its previous close of 12,530.30.
The broader market was also remained under pressure, with the Sensex falling around 300 points and Nifty 50 declining nearly 100 points. Meanwhile, India VIX, often referred to as the market's fear gauge, climbed nearly 1.5 percent, indicating heightened nervousness in the investors.
Metal stocks under pressure: Hindustan Zinc top loser
Selling was broad-based across the metals pack, with most constituents of the Nifty Metal index trading lower.
Hindustan Zinc emerged as the biggest losers on the index, declining 3 percent. Shares of SAIL, NALCO and Hindustan Copper also fell between 2 and 3 percent.
Vedanta Aluminium Metal, Hindalco Industries, Adani Enterprises, Vedanta, Tata Steel and NMDC declined between 1 and 2 percent. JSW Steel and APL Apollo Tubes were also trading in the red.
On the other hand, shares of Jindal Stainless and Lloyds Metals and Energy were trading largely trading flat.
Global metal prices under pressure
The weakness in the metal and mining stocks coincided with a decline in international commodity prices, particularly gold which fell more than 1 percent today, as a firmer US dollar and expectations of higher interest rates in the US reduced the appeal of non-yielding assets.
Spot gold was down 1.4 percent at $3,796.37 per ounce, as of 0242 GMT, after hitting its lowest level since September 2025, reported Reuters.
US gold futures for December delivery dropped 1.7% to $3,799.30.
According to Kelvin Wong, senior market analyst at OANDA, as quoted by Reuters, “The bearish movement in gold prices have been primarily driven by sentiment and technicality, with hawkish reaffirmation from Fed officials and a push up in the US Treasury yields in turn leading to a firmer US dollar," said Kelvin Wong, senior market analyst at OANDA.”
Metal players starred in Q2 show
The weakness in global metal prices is emerging as a fresh concern for domestic metal companies after the sector emerged as one of the biggest contributors to corporate earnings growth in the July-September quarter of the financial year 2026-27. While higher commodity prices boosted profitability in Q2 FY27, a recent moderation in base metal prices could put pressure on producers of aluminium, zinc and copper in the coming quarters.
A Motilal Research note on Q2 FY27 earnings, a fifth of incremental Q2 earnings growth was contributed by the metals sector alone. The others following it were oil excluding OMCs, private banks and NBFCs, but with significantly lower contribution compared to metals. Since much of this earnings growth was on the back of higher prices, that trend sustaining is crucial for growth to also continue. However, with a substantial portion of the earnings growth driven by higher commodity prices, the sustainability of the price rally will be crucial for maintaining the momentum in profitability.
Recent trends in international commodity markets suggest that some of these tailwinds may be weakening. Base metal prices have come under pressure since April, with aluminium prices taking a sharp dip since October, zinc has fallen to a lesser extent and copper has softened in November.
Why are global metal prices falling?
A combination of unfavourable macroeconomic factors and industry-specific developments has weighed on commodity prices. One of the major concerns has been the growing uncertainty surrounding the artificial intelligence (AI) infrastructure investment cycle in the US. There have been doubts cast on the AI infrastructure buildout in the US after the mid-term elections, as also a fear that regulations may slow the march of generative AI models.
Copper, in particular, has benefited from expectations of rising demand from AI-related infrastructure, including data centres and power networks. Any moderation in these investment expectations could therefore weigh on the metal's price outlook.
However, the bigger headwind for many commodities that also have a futures market is the increase in US bond yields and the dollar’s strength. These metals' prices typically soften in an environment like this, which is why bullion is also taking a beating after giving glorious returns in 2025. Commentary from Fed officials points to a hawkish approach to tackling rising prices, which is bad news for commodities that serve as investment or speculative alternatives.
Aluminium, zinc and copper face industry-specific headwinds
Apart from macroeconomic pressures, industry-specific reasons also at play in this. Aluminium prices have declined partly due to the Middle East supply outlook improving, as smelters in the region are restoring output. Expectations of recovering output from the region have eased concerns over supply availability, putting pressure on prices.
Iron ore prices, meanwhile, are declining mainly due to worries on the demand front while the market is well supplied. China’s economy has not provided a reassuring picture on this front, particularly its real estate market. This week’s economic data too has been a disappointing one, showing industrial output and investment missing estimates.
Domestic steel prices offer some comfort
Despite the weakness in iron ore prices, domestic steel prices have remained relatively firm, offering some reassurance to Indian steel producers.
A recent Nomura Research note pointed to China’s exports declining in October, due to a new export licensing policy. The government appears to be keen on supporting steel prices and pushing back against accusations of having excess capacity. The note also points to moderation in steel output in November, which ensures that demand-supply conditions remain favourable from the pricing viewpoint.
The erosion in prices of base metals is likely to put some pressure on producers of aluminium, zinc and copper. However, prices remain elevated compared to a year ago, which will ensure YoY growth looks healthy while sequential growth may feel some heat. On the steel front, keep a close watch on global steel prices to see if rising interest rates in the US and Europe lead to a material weakening of demand for steel. That could create a surplus steel situation that can weigh on prices.